
PERS vs Social Security: Which Will Replace More of Your Salary in Retirement?
If you're a Mississippi PERS member trying to figure out how much of your retirement income will come from PERS versus Social Security, you're asking the right question. The answer depends on your salary, years of service, and when you claim Social Security.
In this post, you'll see how PERS and Social Security work together at different salary levels, why the timing of your Social Security claim matters, and what your own “magic service milestone” might look like. If you’re late in your career and want a clearer picture of retirement readiness, the breakdown that follows will help you think through your next retirement planning step.
How PERS and Social Security Work Together
To compare PERS vs Social Security retirement income, you first need to understand that they do not replace salary in the same way. PERS tends to grow with years of service and salary, while Social Security is more progressive and eventually capped at a lower level of compensation.
That difference matters because the makeup of your retirement income changes depending on your earnings level. At lower salaries, Social Security makes up a larger share of fixed retirement income. At higher salaries, PERS makes up a larger share of fixed retirement income.
PERS and Social Security Retirement Income Model
To help PERS members visualize this transition, we modeled fixed retirement income coming from PERS and Social Security across salaries ranging from $50,000 to $500,000, across years of service ranging from 25 to 40 years, and across Social Security claiming ages ranging from 62 to 70.
The assumptions behind our model
The PERS member was hired before July 1, 2011 (making them Tier 1, Tier 2, or Tier 3)
The PERS member selects the maximum retirement allowance option
Salary at the end of the career is used as the highest four average compensation for PERS purposes and average indexed monthly earnings (AIME) for Social Security purposes
PERS highest four average compensation was capped at $330,000 (2023 limit)
Social Security AIME was capped at $12,000 for someone who has earned the maximum earnings since age 22 (2026 estimate)
The PERS member was born in or after 1960 (making 67 their full retirement)
These assumptions matter because they make the comparison cleaner. They also mean this is a planning model, not a personalized retirement calculation. Still, it gives you a useful way to estimate how much of your future income could come from each government-backed system.
One of the most useful things to understand is that fixed retirement income can eventually surpass your working salary - but not for everyone, and not at the same pace. That’s where the idea of a “magic service milestone” comes in.
What Your “Magic Service Milestone” Might Be
Your magic service milestone is the point where your combined PERS and Social Security retirement income equals or exceeds your pre-retirement salary. In other words, it’s the years of service where your fixed retirement income catches up to what you were making while working.
That milestone changes a lot based on your salary and when you plan to claim Social Security.
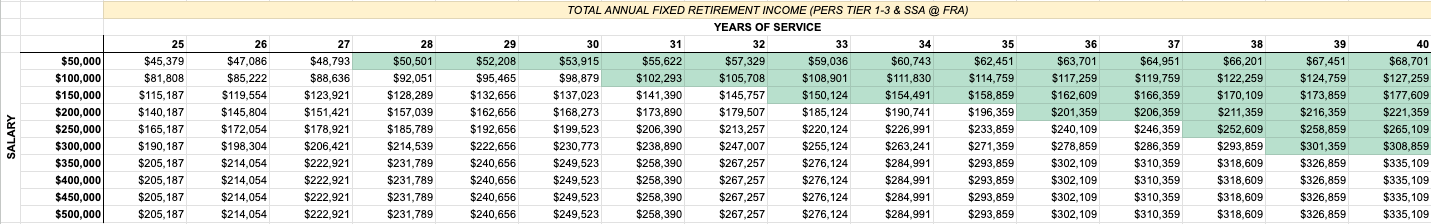
Annual Total Retirement Income from PERS and Social Security at Various Years of Service and Salaries and Claiming Social Security at 67
When Social Security is claimed at 67 (full retirement age), the model showed that:
At $50,000, the milestone arrives at 28 years of service
At $100,000, it arrives at 31 years of service
At $150,000, it arrives at 33 years of service
At $200,000, it arrives at 36 years of service
At $250,000, it arrives at 38 years of service
At $300,000, it arrives at 39 years of service
At $350,000 and above, it does not surpass pre-retirement salary within 40 years
That last point is important. Because PERS compensation eventually caps out in the model, very high earners may never fully replace working salary with fixed income alone, at least not within the service range studied.
A separate point about the total fixed retirement income numbers you see in the table above and will see in the tables that follow below: the model’s fixed retirement income totals will not match your real-world retirement income if you retire from PERS and claim social security in a different year. In that case, either your PERS or Social Security benefit will actually be higher due to annual cost-of-living-adjustments.
For example, if you retire from PERS at 58 but don’t claim Social Security until 67, your PERS pension will increase with COLA until you claim Social Security at 67, which will make your actual total fixed retirement income higher than what is shown in the table above. But that only works if you have another source of income to cover the gap left from Social Security from age 58 to age 67.
Retirement Planning Opportunity
The higher your salary, the longer it may take for PERS plus Social Security retirement income to match what you earn today. And if your salary is very high, you may need other retirement assets to close the gap.
Another key pattern showed up in the data: PERS becomes a larger share of your fixed income as years of service rise. That makes sense because Social Security has a benefit formula that is more progressive and less directly tied to high earnings once you hit the AIME cap.
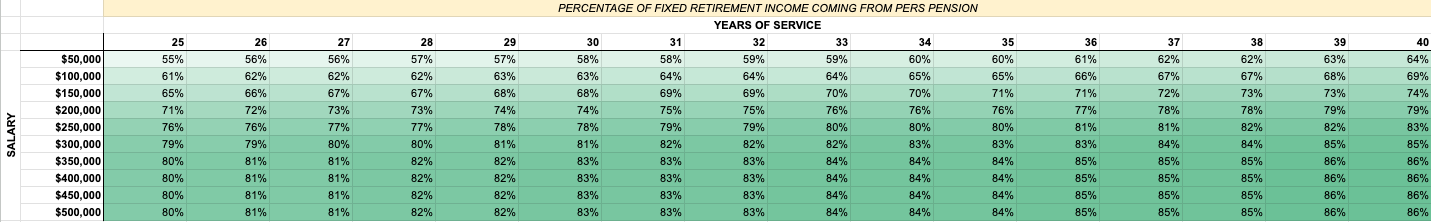
Percentage of Fixed Retirement Income Coming from PERS at Various Years of Service and Salaries and Claiming Social Security at 67
At $50,000 salary and 25 years of service, PERS made up 55% of fixed income. At the other extreme, with salaries above $350,000 and 35 years of service, PERS made up 84% of fixed income. In other words, the longer you work and the more you earn, the more your retirement income comes from PERS pension.
How Claiming Social Security Early Changes the Picture
The age you claim Social Security can dramatically change how quickly your retirement income catches up to salary. That’s because claiming early reduces the benefit, while delaying boosts it.
When Social Security is claimed at age 62, the reduced benefit means you need more years of service to reach the same income replacement level.
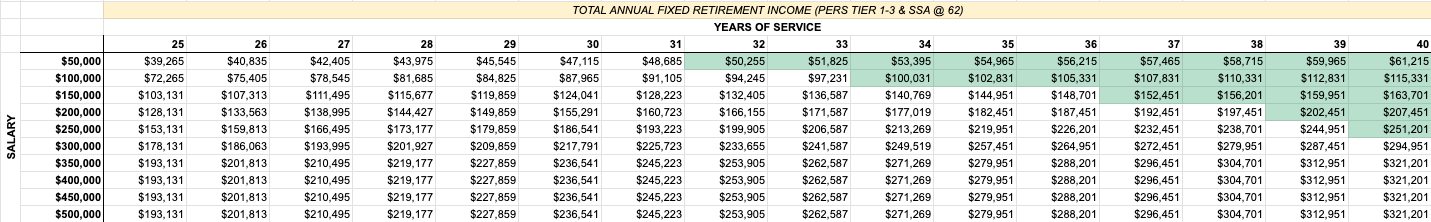
Annual Total Retirement Income from PERS and Social Security at Various Years of Service and Salaries and Claiming Social Security at 62
When Social Security is claimed at 62 (earliest age), the model showed that:
At $50,000, the milestone arrives at 32 years of service
At $100,000, it arrives at 34 years of service
At $150,000, it arrives at 37 years of service
At $200,000, it arrives at 39 years of service
At $250,000, it arrives at 40 years of service
At $300,000 and above, it does not surpass pre-retirement salary within 40 years
That’s a meaningful shift compared with claiming at 67. At $50,000, for example, you need 4 extra years of service if you claim Social Security early at 62 instead of full retirement age at 67.
Retirement Planning Opportunity
Claiming early can reduce Social Security by 30%. Since Social Security is then a smaller piece of the pie, PERS has to do more of the work in retirement.
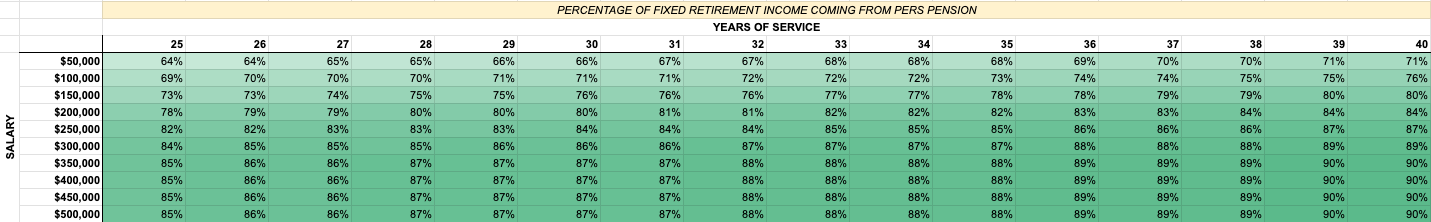
Percentage of Fixed Retirement Income Coming from PERS at Various Years of Service and Salaries and Claiming Social Security at 62
At $100,000 salary and 30 years of service, PERS accounts for 71% of fixed retirement income when claiming at 62, compared with 63% when claiming at 67.
Why Delaying Social Security Can Actually Help You Reach Your Retirement Goal Sooner
If claiming early slows down income replacement, delaying Social Security can speed it up. In the model, claiming Social Security at age 70 pushed the milestone earlier across every salary level.
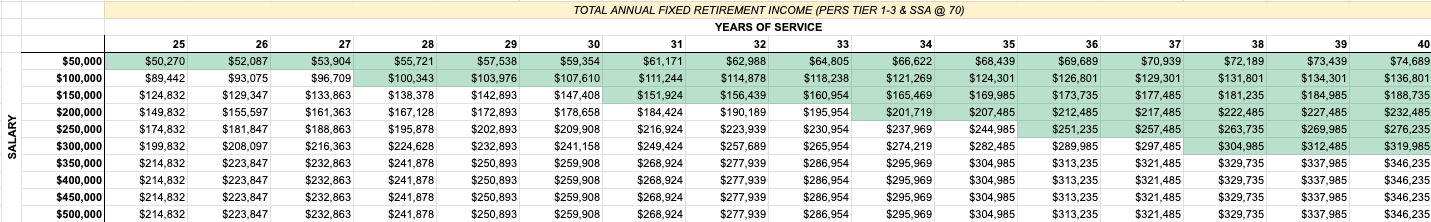
Annual Total Retirement Income from PERS and Social Security at Various Years of Service and Salaries and Claiming Social Security at 70
When Social Security is claimed at 70 (latest age), the model showed that:
At $50,000, the milestone arrives at 25 years of service
At $100,000, it arrives at 28 years of service
At $150,000, it arrives at 31 years of service
At $200,000, it arrives at 34 years of service
At $250,000, it arrives at 36 years of service
At $300,000, it arrives at 38 years of service
At $350,000 and above, it does not surpass pre-retirement salary within 40 years
Compared with claiming at 67, delaying to 70 can shave off roughly 3 years of service needed in several salary bands.
Retirement Planning Opportunity
Delaying claiming can increase Social Security by 24%. Since Social Security is then a larger piece of the pie, PERS has to do less of the work in retirement.
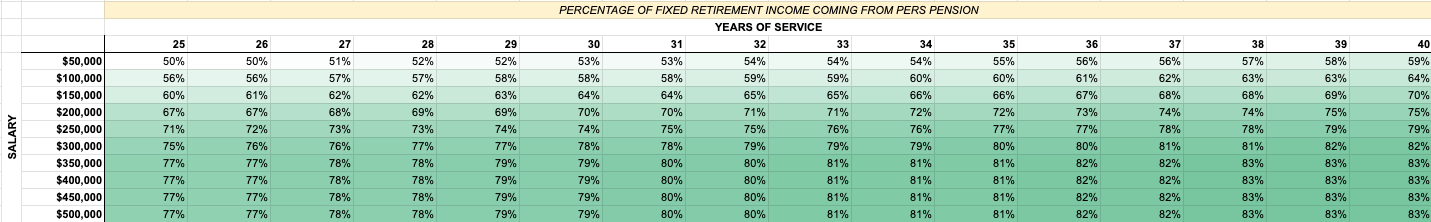
At $100,000 salary and 30 years of service, PERS made up 58% of fixed income when claiming social security at age 70, compared with 63% at age 67.
PERS Retirement & Social Security Claiming Dates May be Different
Your retirement date and your Social Security claim date should not be treated as the same decision. If you retire from PERS at one age and claim Social Security later, you may need enough assets or income to bridge the gap.
That bridge can come from:
Cash savings
Deferred compensation
IRA distributions
Brokerage accounts
Part-time work
Spousal income, if applicable
Inherited assets
The best choice depends on your broader financial picture. But if you’re planning retirement, you should at least know what that gap is and how long it lasts.
What Late-Career PERS Members Should Do Next
#1 - Determine your primary income driver
Compare your current salary with the model ranges to see whether PERS or Social Security is likely to provide the larger share of your fixed retirement income.
#2 - Find your magic service milestone
Estimate the age and years of service where your combined retirement income may match or exceed your working salary.
#3 - Check for income gaps
If you plan to retire before claiming Social Security, identify how much additional savings you’ll need to bridge the years in between.
Frequently Asked Questions
Which provides more retirement income, PERS or Social Security?
It depends on your salary, years of service, and when you claim Social Security. At lower salary levels, Social Security may represent a larger share of fixed income, but PERS often becomes the dominant source as salary and service increase.
What is the “magic service milestone”?
It’s the point where your combined PERS and Social Security retirement income equals or exceeds your pre-retirement salary. That milestone changes based on your salary and the age you claim Social Security.
Does claiming Social Security at 62 hurt retirement income?
Usually yes, if your goal is to maximize lifetime benefits. Claiming at 62 permanently reduces Social Security, which often means you need more years of service or more outside savings to replace your salary.
Is delaying Social Security until 70 always the best move?
Not always, but it can increase monthly benefits significantly. Whether that’s the best choice depends on your health, cash flow needs, retirement date, and whether you can afford the years before claiming.
Can PERS and Social Security fully replace my salary?
Sometimes, but not for everyone. Lower and middle salary levels with enough years of service may reach or exceed working salary, while higher salary levels may not fully replace income.
Final Thoughts
For many people, this is the part of retirement planning that brings the most clarity. You may discover that your pension is doing more of the heavy lifting than you expected. Or you may realize that Social Security timing has a larger impact on your retirement income than you thought.
The biggest lesson from this model is encouraging: even if you started saving late, you may still have strong retirement income through PERS and Social Security alone.
As an example, someone who doesn’t save anything for retirement before the age of 45, who then finds a job and works for a PERS employer for 25 years making $50,000 at their end of their career, who retires from PERS and begins claiming Social Security at age 70, will reach retirement with inflation-adjusted government-backed income that surpasses their working salary.
This is a powerful reminder that proper retirement planning can bring hope and clarity to an otherwise uncertain concept.
Disclaimer: This post is for educational and informational purposes only and is not to be construed as personal financial, investment, tax, or legal advice. We cannot guarantee the accuracy in the future as federal and state laws change. Always consult a professional for personal advice specific to your situation.
